

LULU
Lululemon Athletica Inc
lululemon: a confession
Lululemon and I have a troubled relationship.
While I still believe in the company, but after this and my Nike investment... I think it's time to consider Apparel outside of my Circle of Competence.
And with a P/E around 8, I find myself eyeing out the stock again.
Well, if Buffett was an aeroholic, then I may as well consider myself an athleisure-holic...
But, I mean, it couldn't hurt to check... the company has a few good things going for them:
They have a new CEO, announced in April, who started September 8.
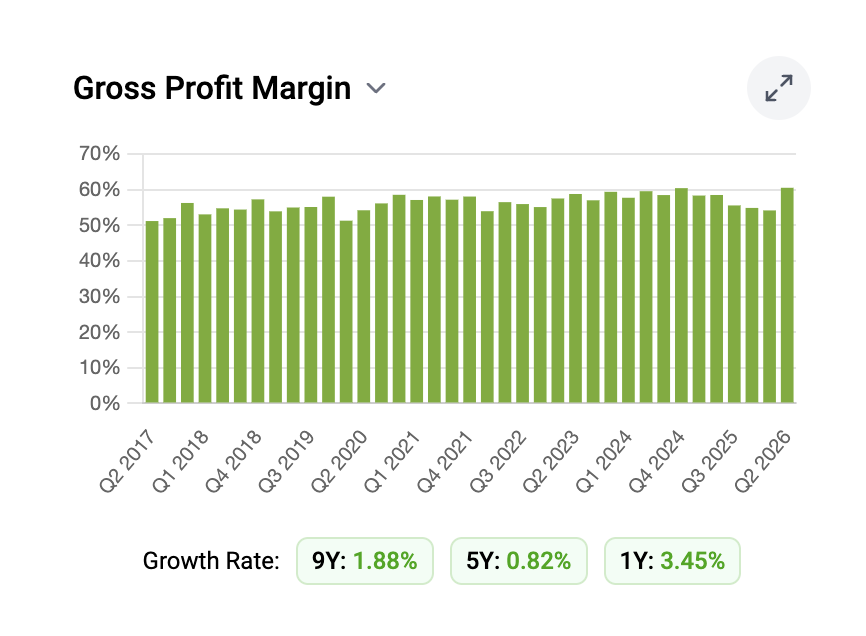
They are protecting gross margins at ~60%!!
And did I say that their P/E ratio is 8?
Oh, and Michael Burry owns the stock.
And disclosure, I still own it. So, after some research, this is where I am:
Quick background since it's been awhile since I've written on lulu
I first bought it because I had admired the brand for years. I walked into my first store with my brother-in-law and walked out with my first four pairs of ABC pants, and I wore the absolute crap out of them. The stock dipped during the pandemic and I never jumped, because I thought it was overpriced. When it fell again in 2023-2024, I bought.
The Numbers
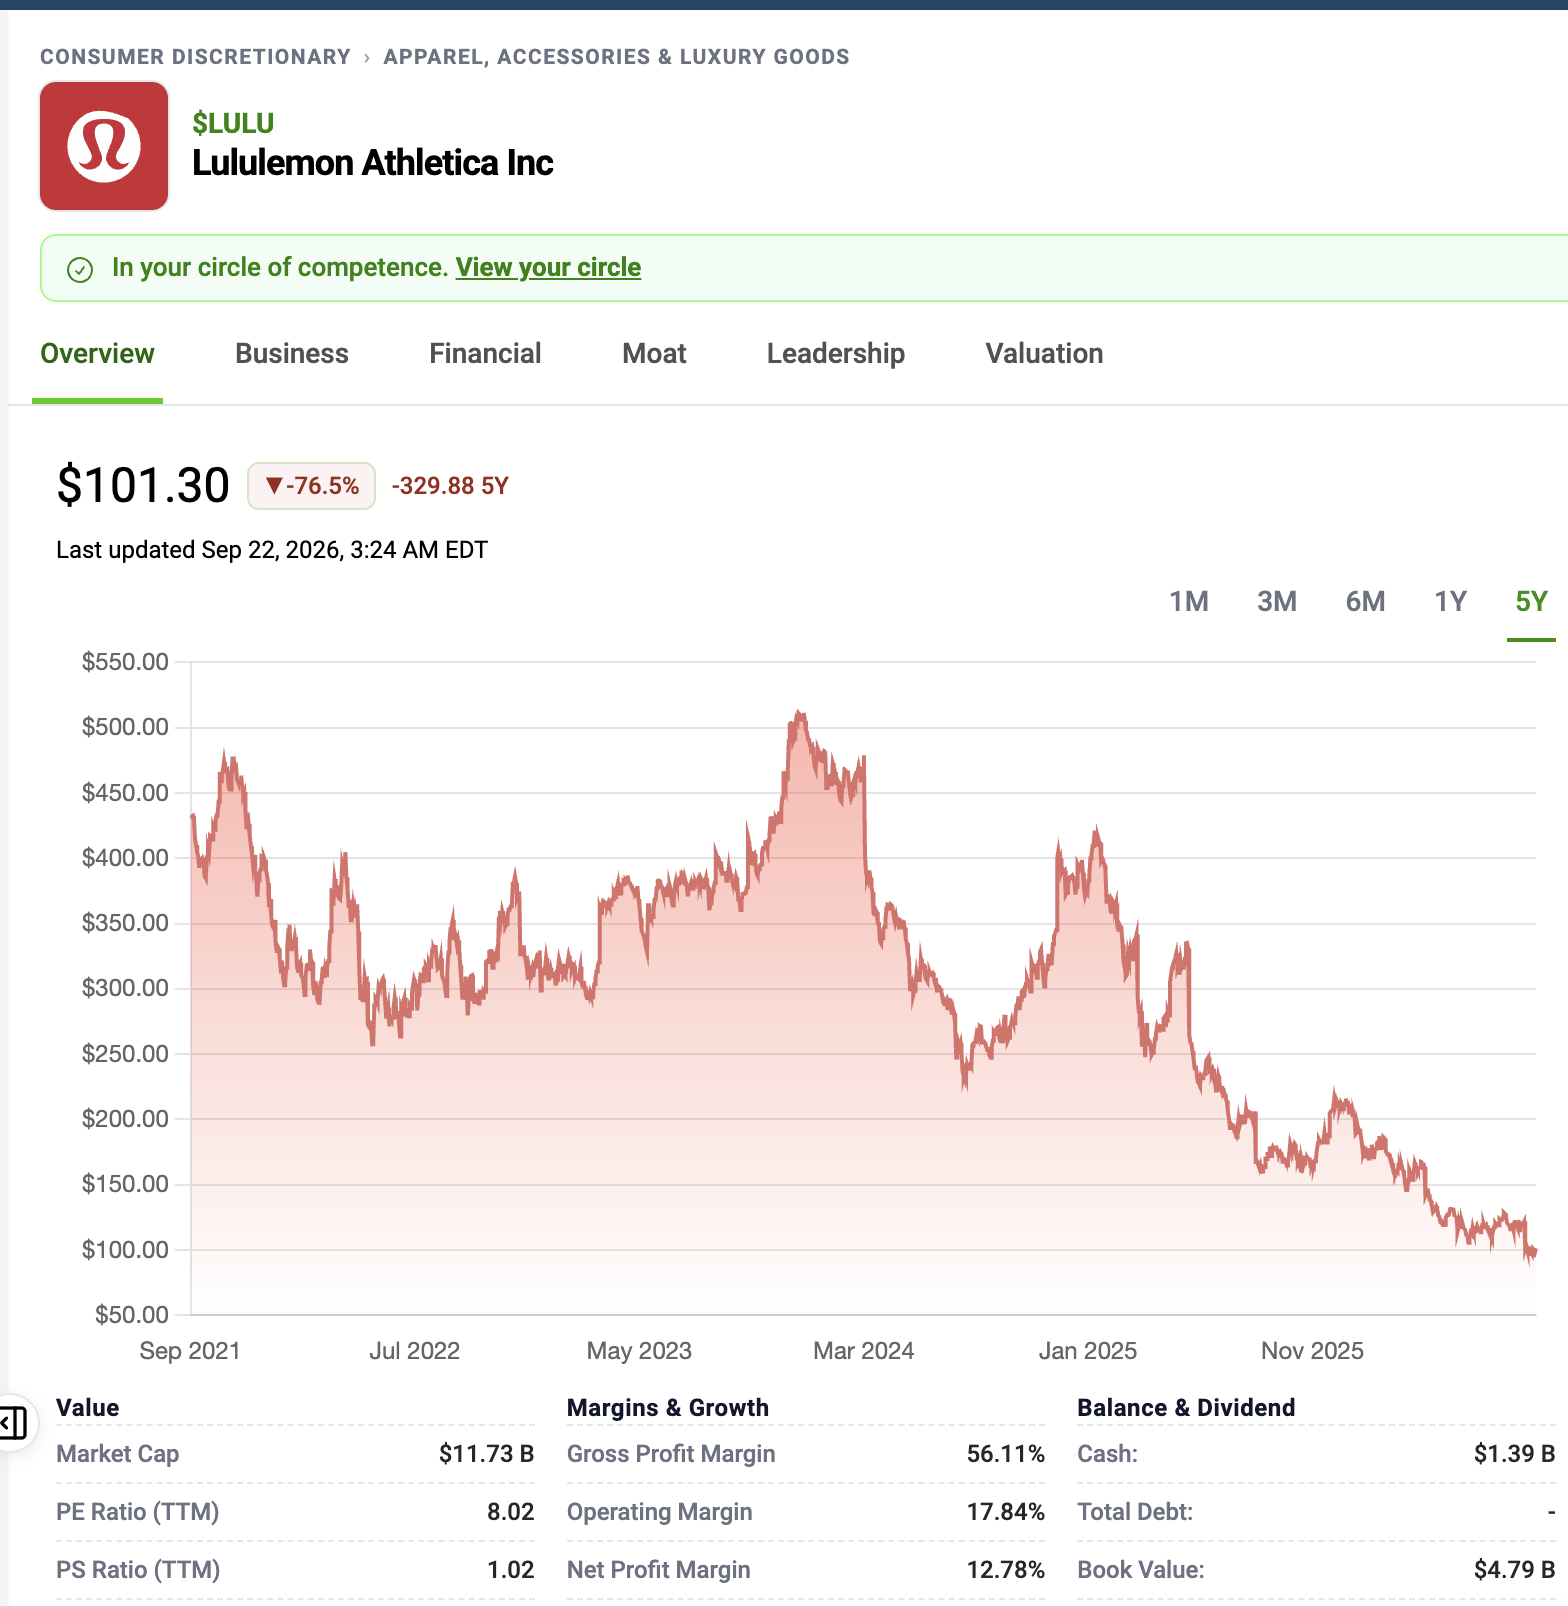
The stock peaked around $511 in December 2023. It's around $100 today.
That's an 75% drop.
The quarter that broke it ended August 2 and was reported September 3:
Revenue fell 4% to $2.4 billion.
Comparable sales, meaning the same stores and website versus a year ago, fell 9%, and 12% in the Americas.
Net income fell to $329 million from $371 million.
About those gross margins I bragged about up top... 60.5% looks great, but $134.5 million of it was a one-time tariff refund (whoops)
Take that out and margin actually fell, from 58.5% to about 55%.
Then they cut the full-year forecast for the second time this year, to $9.48 to $9.73 a share, down from $13.26 last year. They also expect next quarter's sales to drop 10% to 11%.
What's still true: $1.4 billion in cash, no debt, and $330 million of buybacks in one quarter. At around $100, that's about 8 times the last twelve months of earnings, and about 10 times this year's shrinking forecast.
My Reservations
1. After Nike, I'm not sure apparel is in my circle of competence.
Circle of competence isn't about knowing the product. I know ABC pants better than most analysts.
It's about knowing what the business looks like in ten years, and I thought I knew that with Nike too. Lululemon's growth ran on a mood and trends I didn't see (I actually did - I remember women I knew telling me the brand had become off-putting to them-- lesson learned!).
2. The brand reads snobby, or old and tired, and the Chip Wilson stuff still lingers.
The numbers agree. Comparable sales fell 12% in the Americas and 3% everywhere else. The home market that built the brand is the one walking away. A new CEO can fix a lot of things, but getting Americans to want the logo again is the hard one.
3. I don't know where it goes from here, but the price is getting really attractive.
It is. But this has entered turnaround territory now, not a growth story, and turnarounds play by different odds.
It's cheap if sales stop shrinking and a trap if they don't. The first real read on the new CEO comes in early December.
Where That Leaves Me
I still own it, and I'm not adding until December shows me the Americas stopped bleeding. A low P/E on shrinking earnings isn't a bargain until the shrinking stops. And if you've watched my videos, you know I'm still wearing the same Lululemon shirts in nearly all of them. The customer in me never left. The shareholder is just being a lot more careful.
Disclosure: I own Lululemon. I first bought during the 2023-2024 drop and have sold some since.
Sentiment: Neutral