

LEN
Lennar Corp
Is now a good time to buy a house? This Struggling Homebuilder says yes
One of my favorite things about studying public businesses is that you get insights into the real world as a consumer.
Lennar, one of the U.S.'s largest homebuilding companies, just had an awful quarter.
Here's what they said at the top of their quarterly results
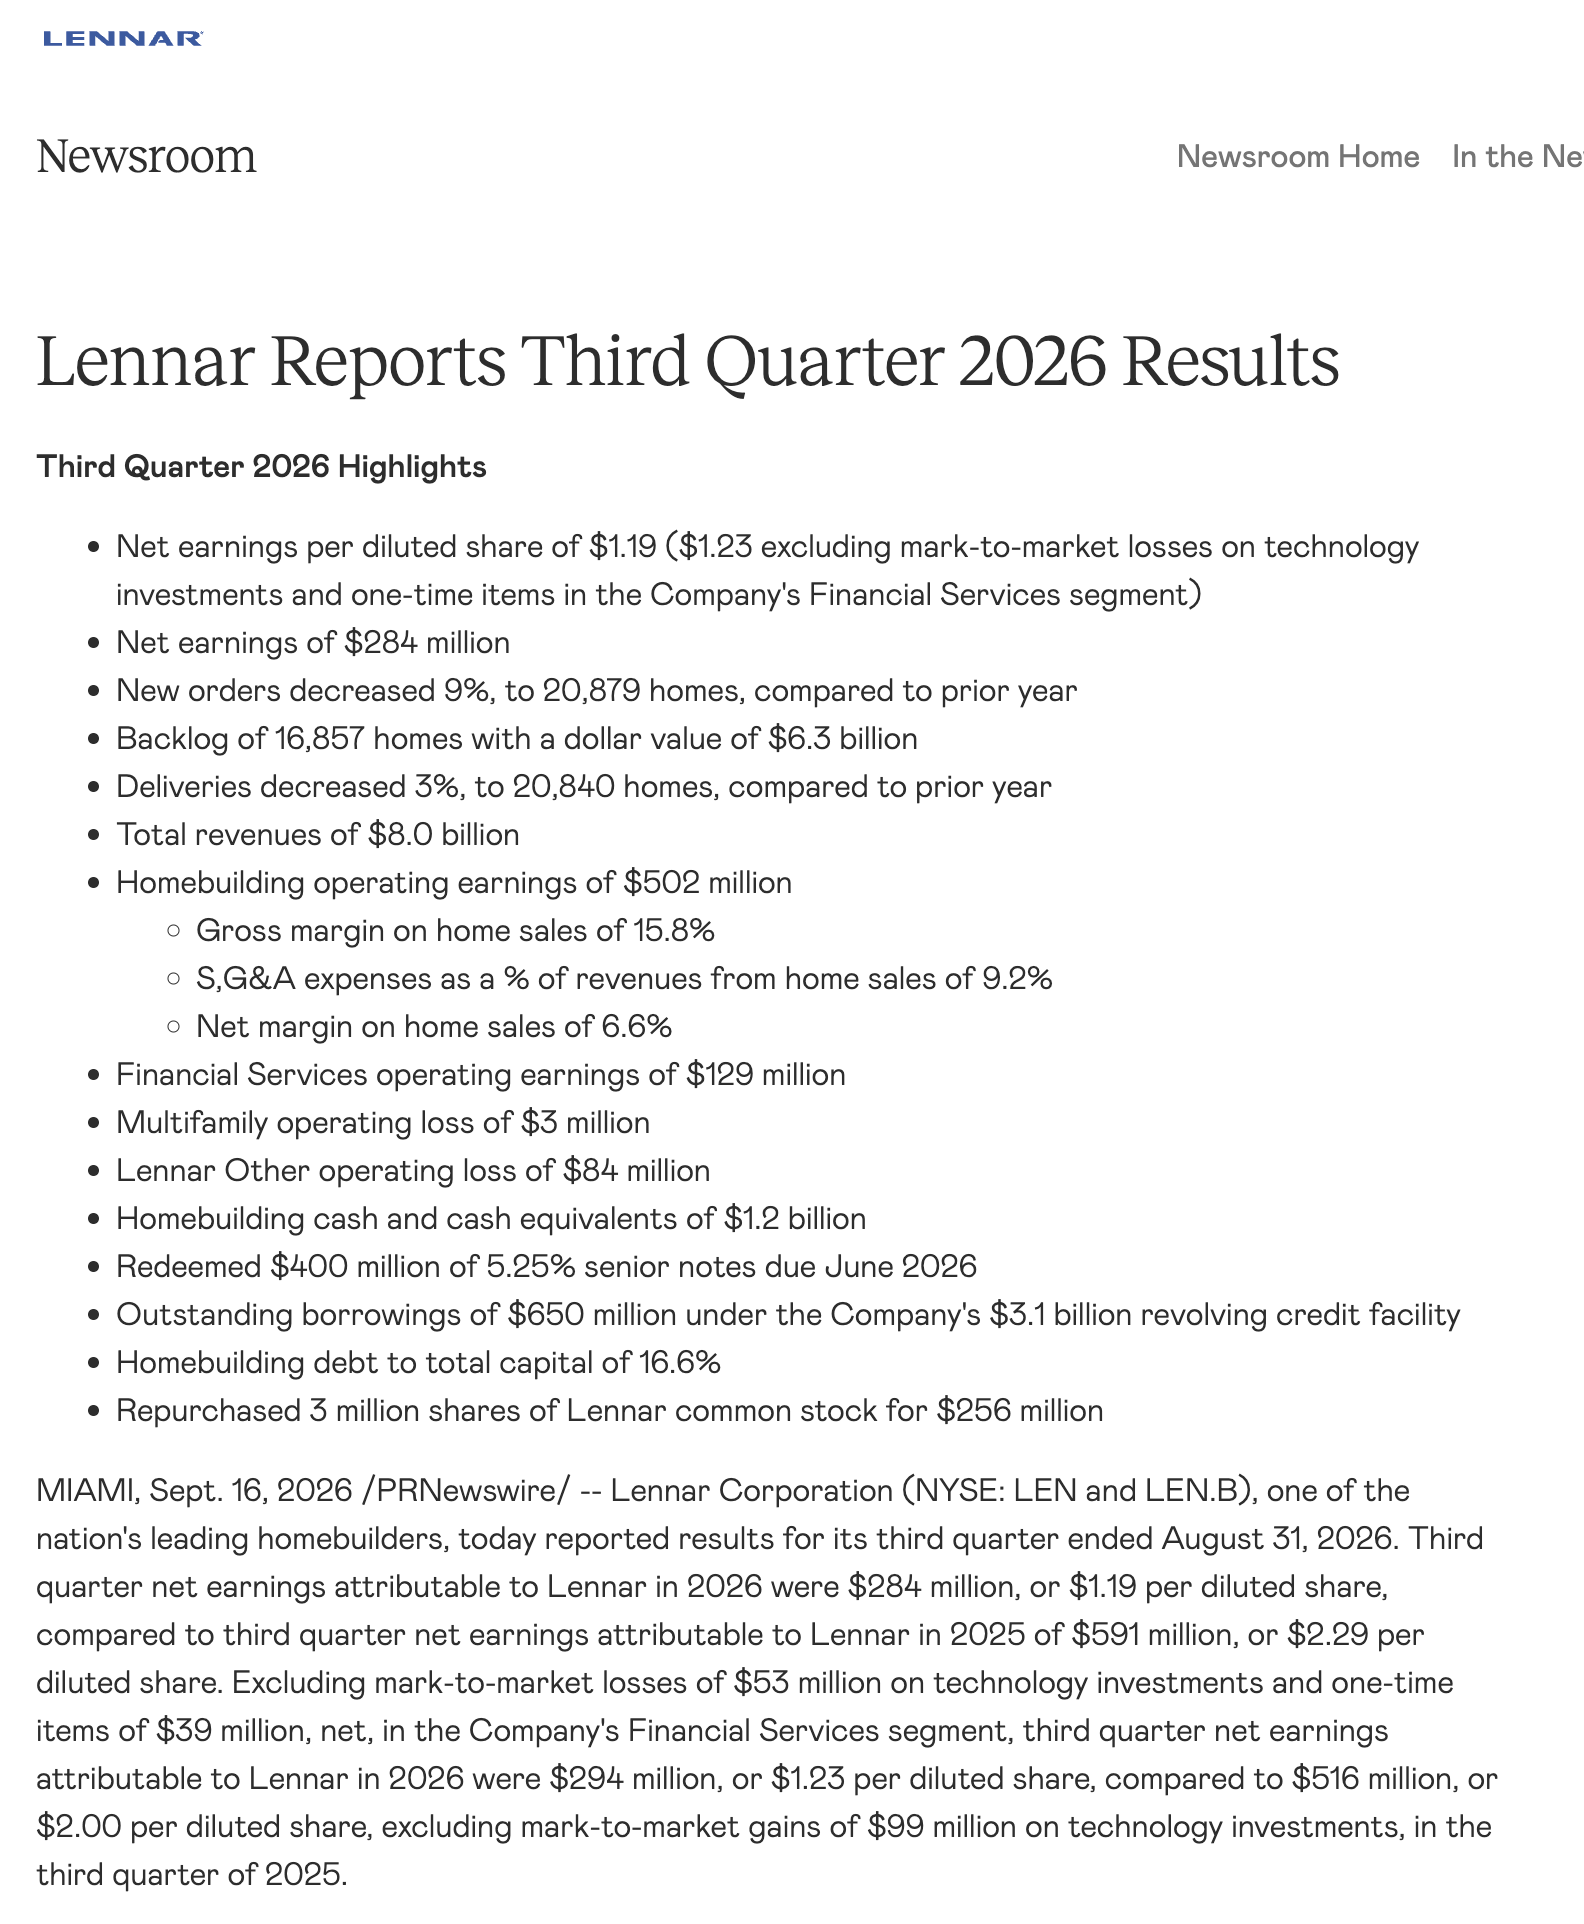
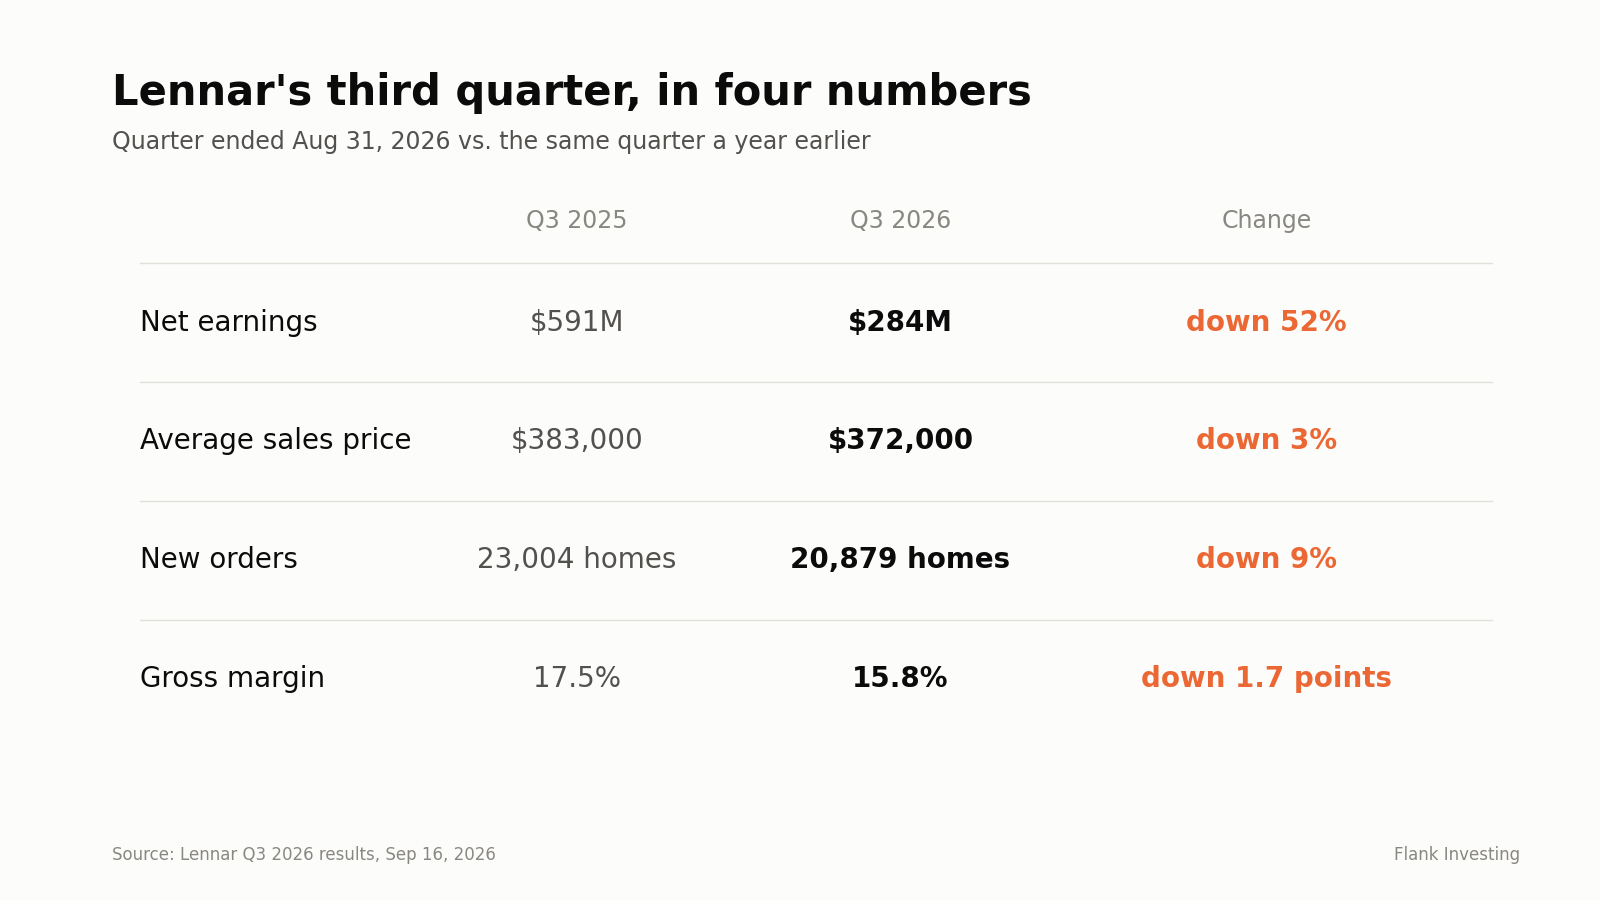
Here's the highlights of the highlights for you:
You can see how much their business is struggling from the Flank overview:
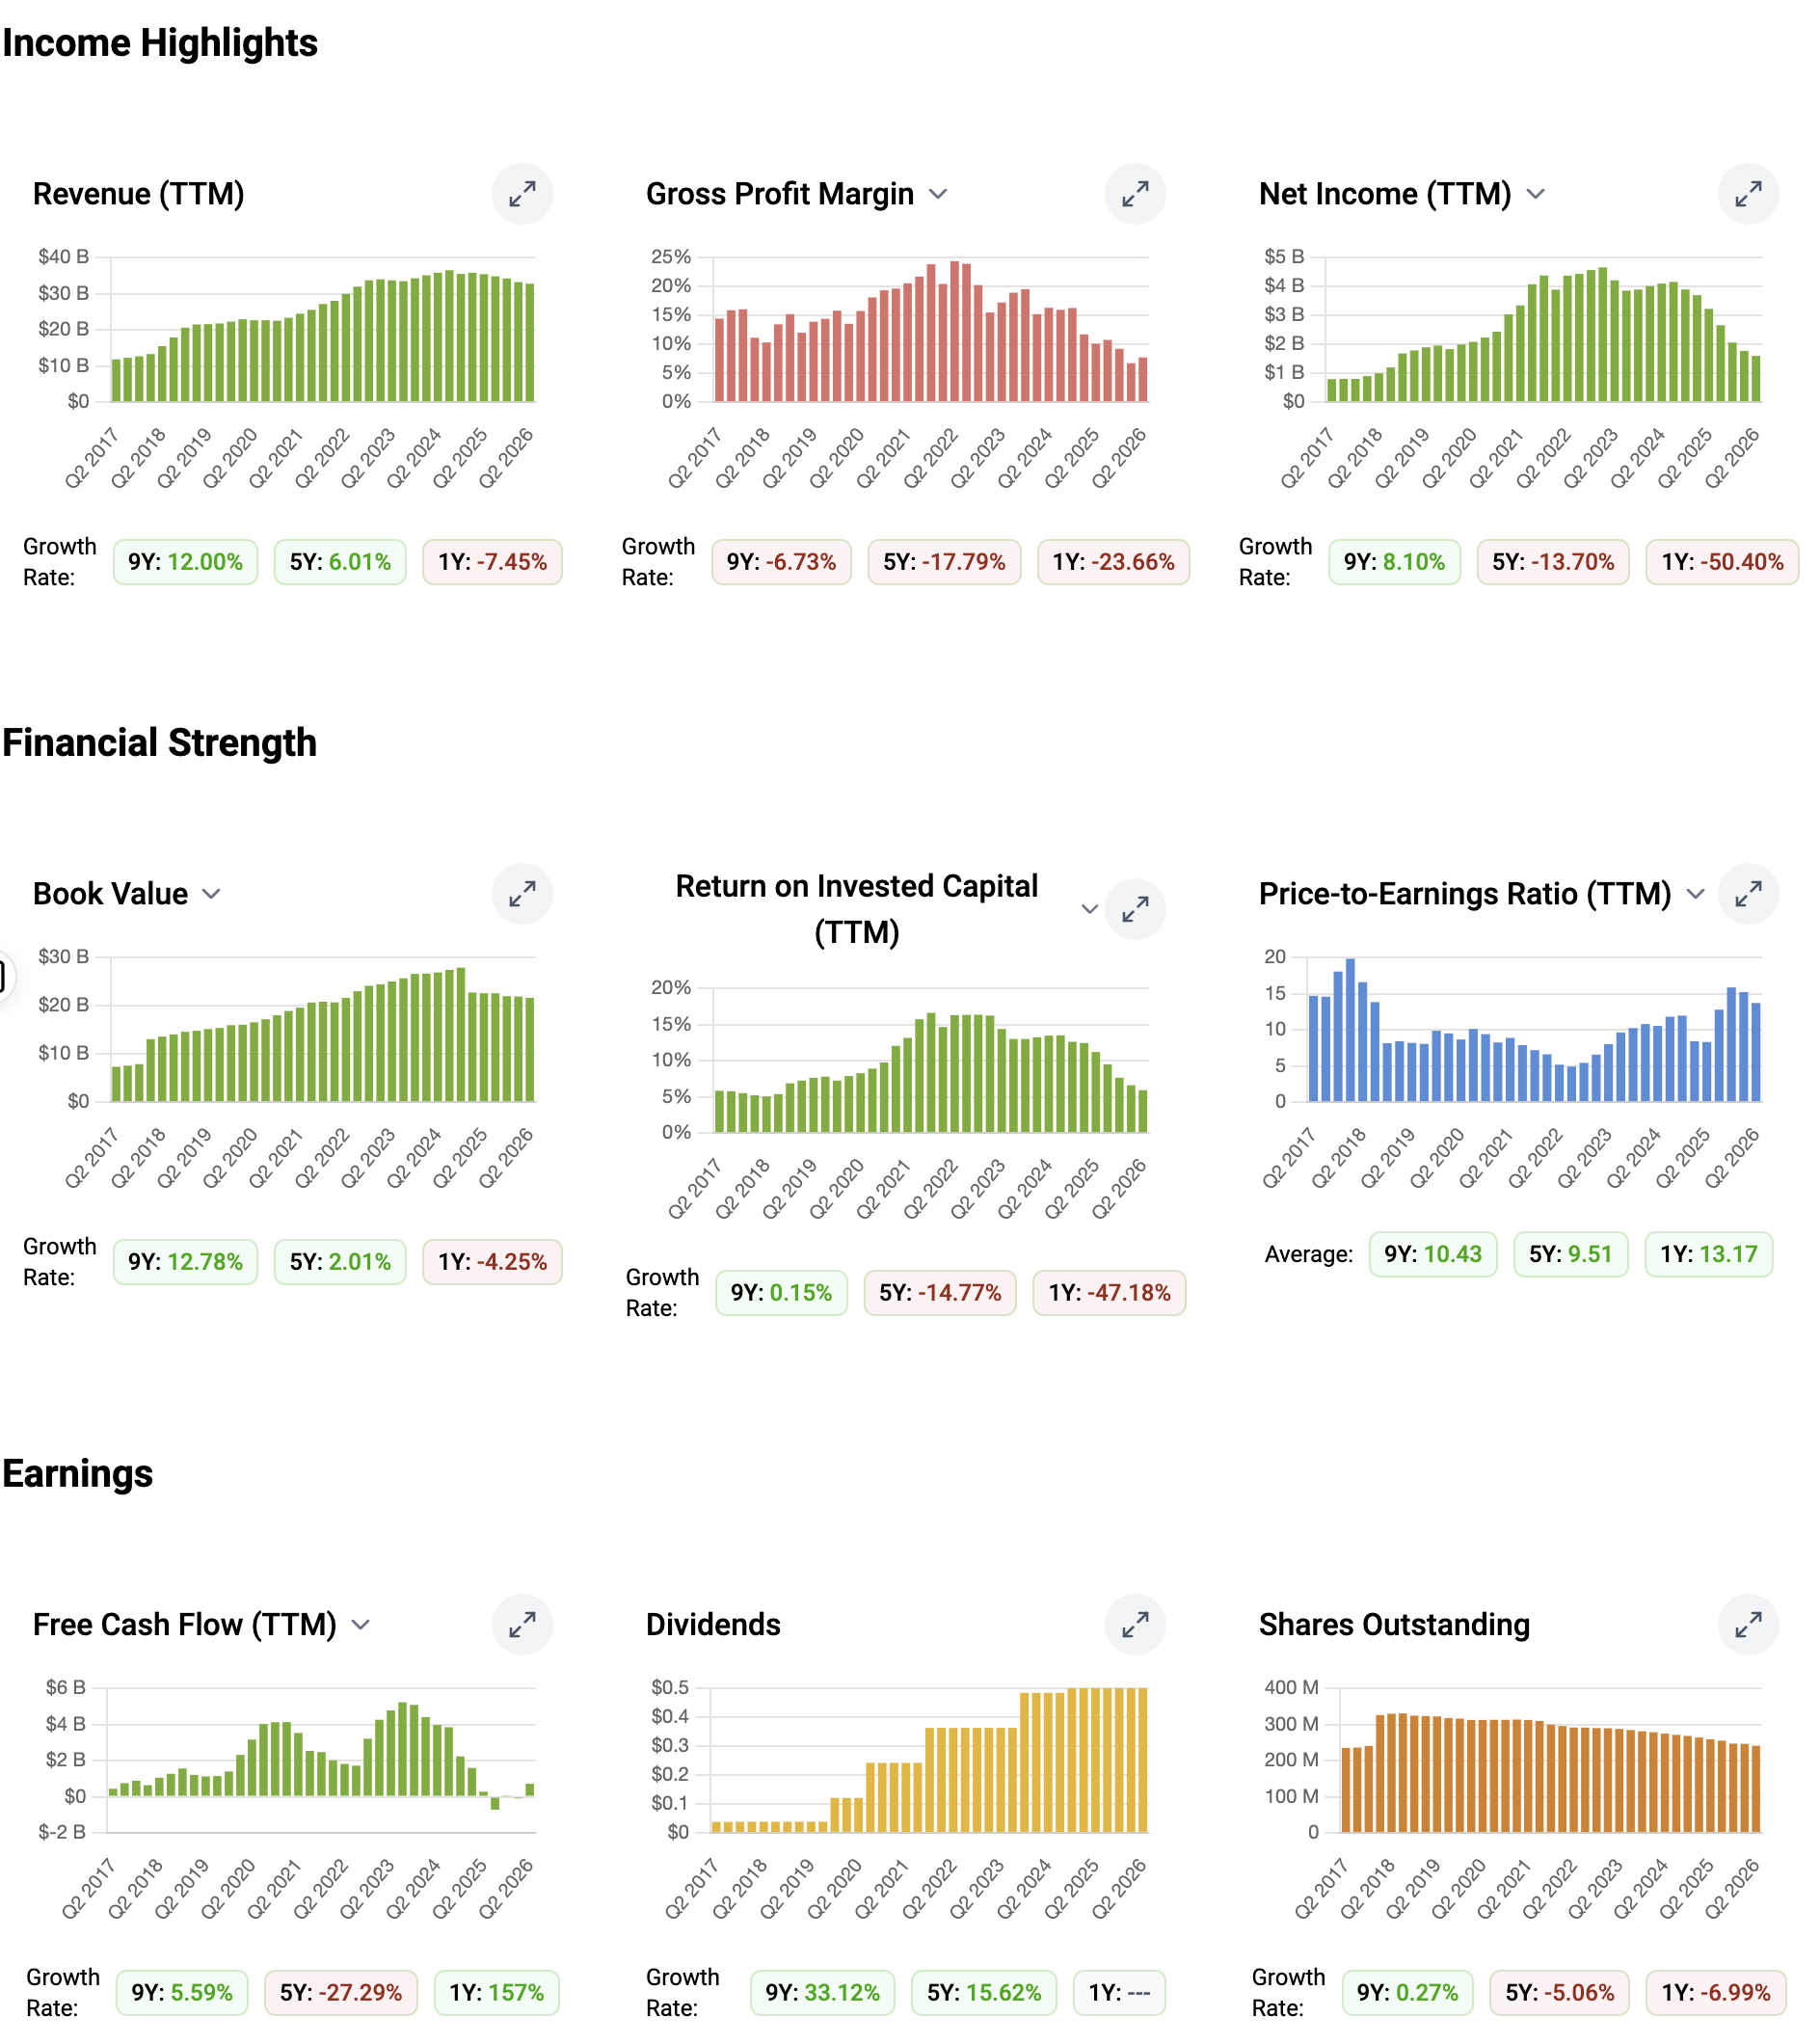
Revenue falling -7.5% over the past year
Gross profit margin down 23% to 7.71% (yikes - thats GROSS profit margin)
Dividends increasing... huh?
The one silver lining? Shares being bought back quite precipitously (-7% shares outstanding... but based on how the business is performing, I'm kind of second-guessing that that's the best use of capital right now.
The stocks not uber cheap either, at 13x trailing earnings. I know Homebuilders are cyclical businesses, but yeesh.
For the quarter that ended August 31, Lennar's net earnings were $284 million, down from $591 million a year ago. Cut in half. New orders fell 9%. The average home sold for $372,000, down from $383,000.
But! This isn't necessarily just a Lennar post...
And to move those homes, Lennar handed buyers "approximately 12% in incentives," per Lennar's own release
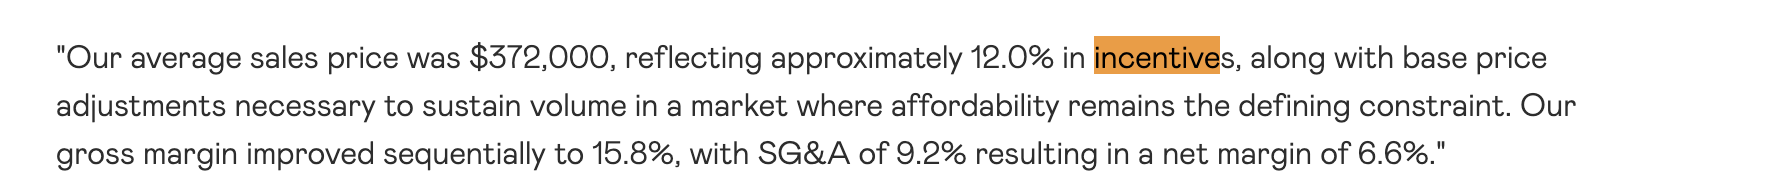
That's what caught my eye. One of the biggest builders in the country is giving buyers 12% off.
So I wanted to ask a question you're not supposed to be able to answer from an earnings release: is now a good time to buy a house?
How Lennar makes money, and where the 12% incentives come from
Lennar buys land (mostly through options, it owns very little outright), builds houses, and sells them. The money is the gap between what it costs to build the house and what you pay for it. That gap, the gross margin, was 15.8% last quarter, down from 17.5% a year ago. After overhead, Lennar kept 6.6% of every home sale.
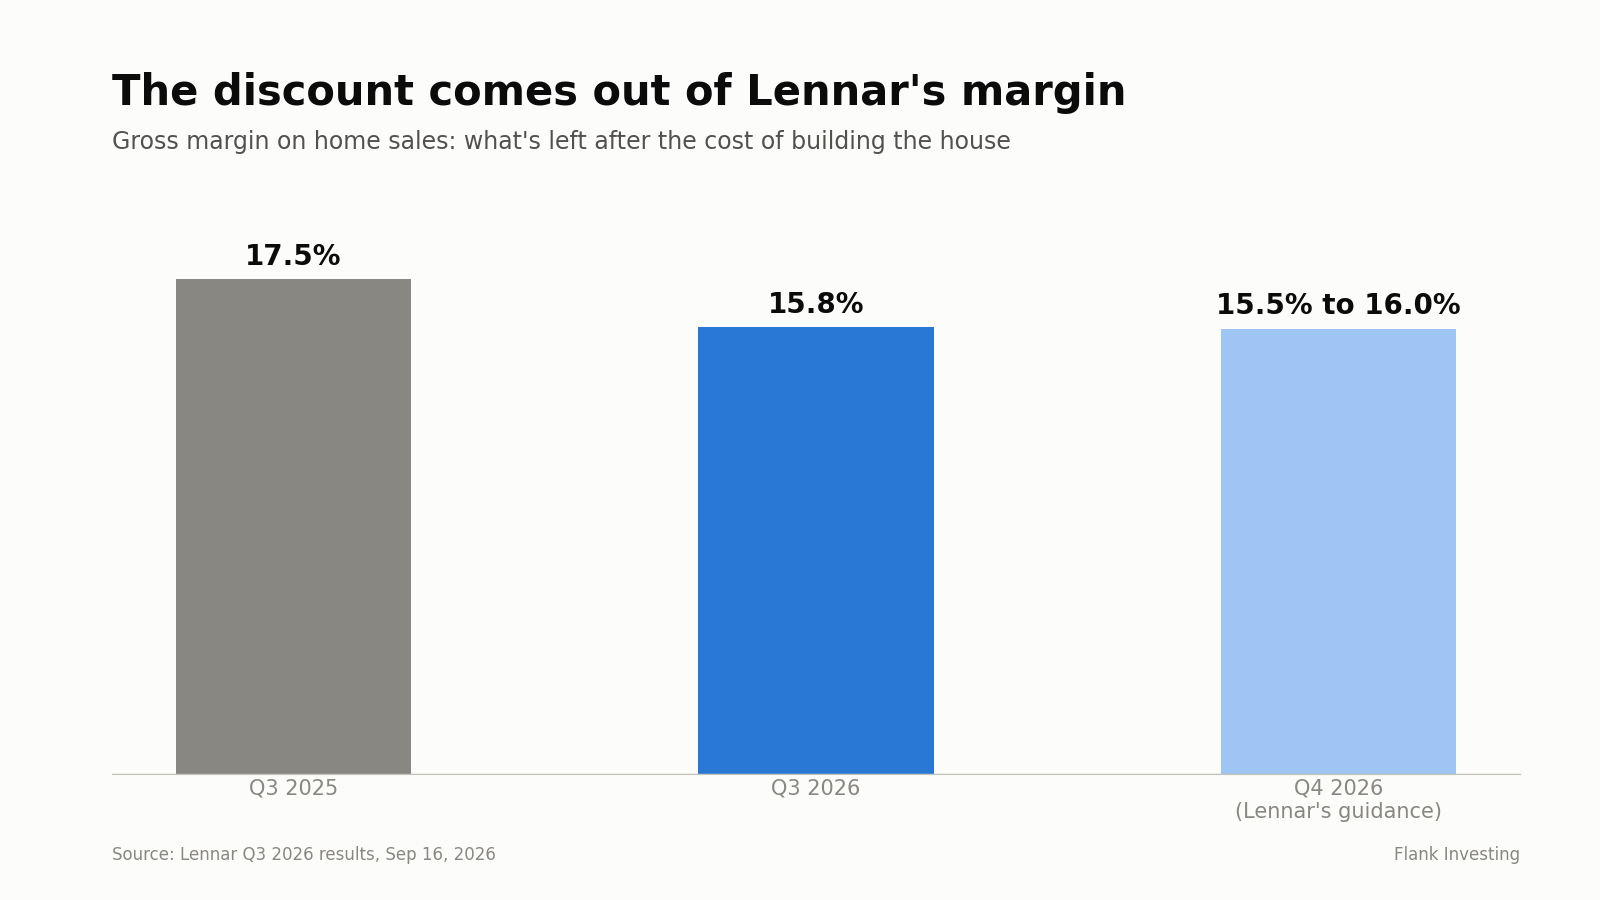
The 12% comes straight out of that gap. It reaches you three ways: a lower price, Lennar paying your closing costs, or Lennar paying to buy down your mortgage rate through its own mortgage arm. Either way it's real money to the buyer and less profit for Lennar.
Why do it? On the earnings call, CEO Stuart Miller said Lennar will not "carry standing homes into a soft market." They would rather sell a house cheap today than hold it and wait.
The line that stuck with me
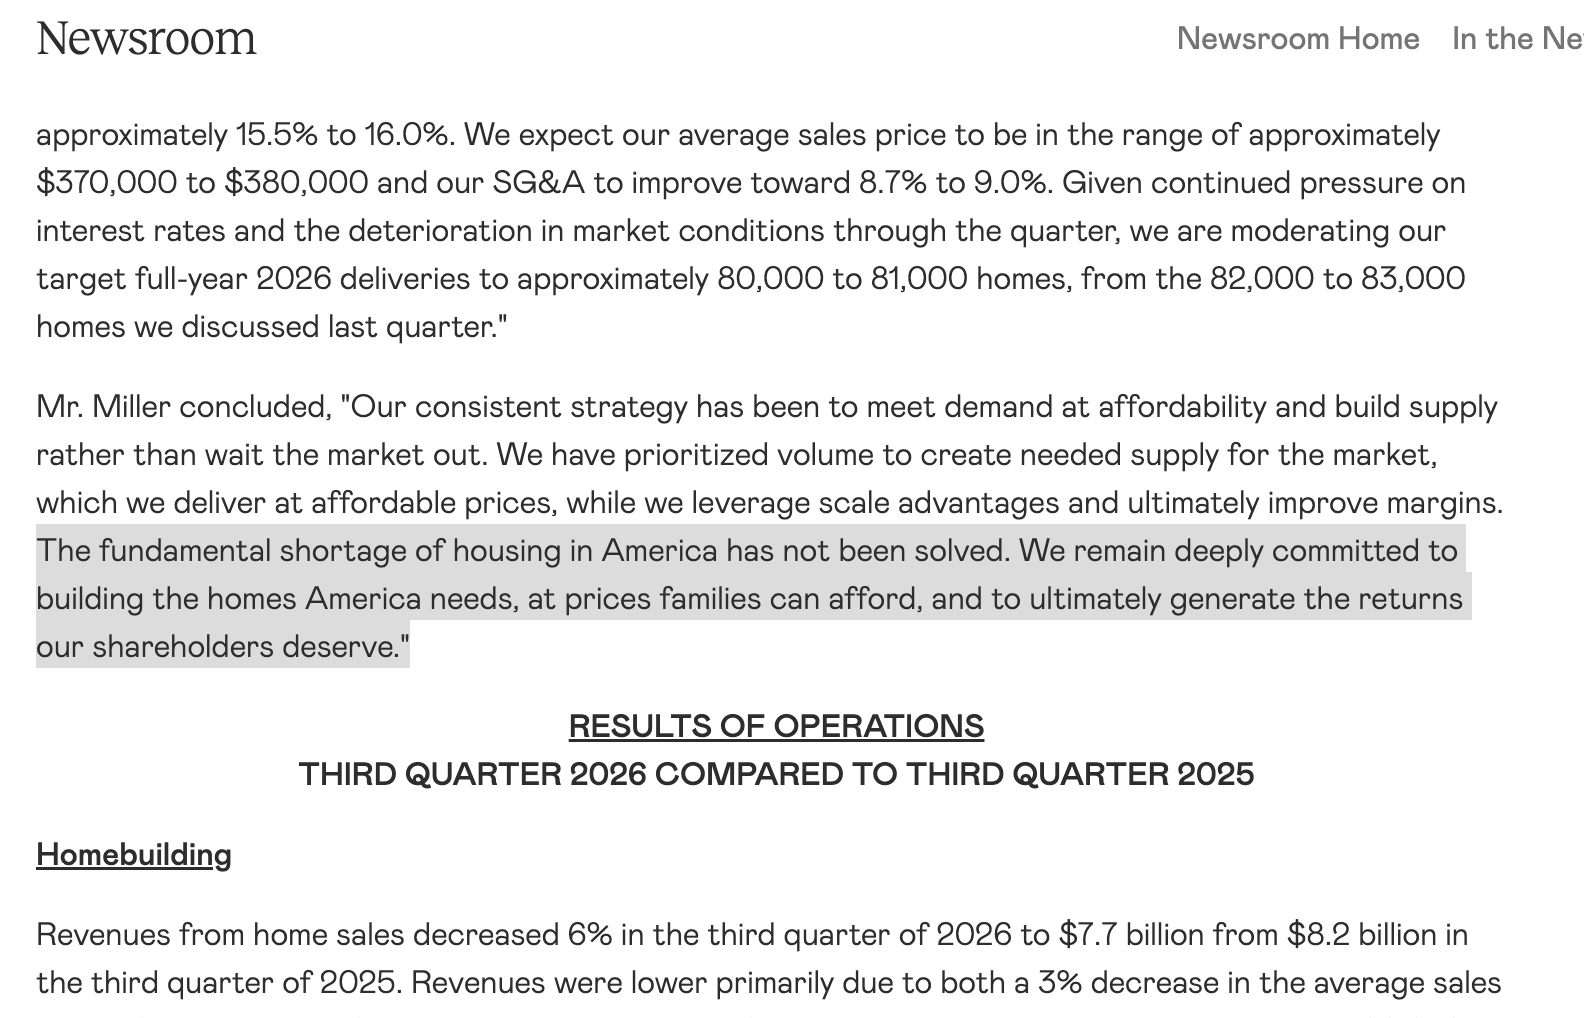
Two more lines from the call.
Miller said the buyer at median family income is "stretching well past 30% of gross income to carry a home," and
that in many markets "almost 50% of our visitors cannot immediately qualify" for a mortgage.
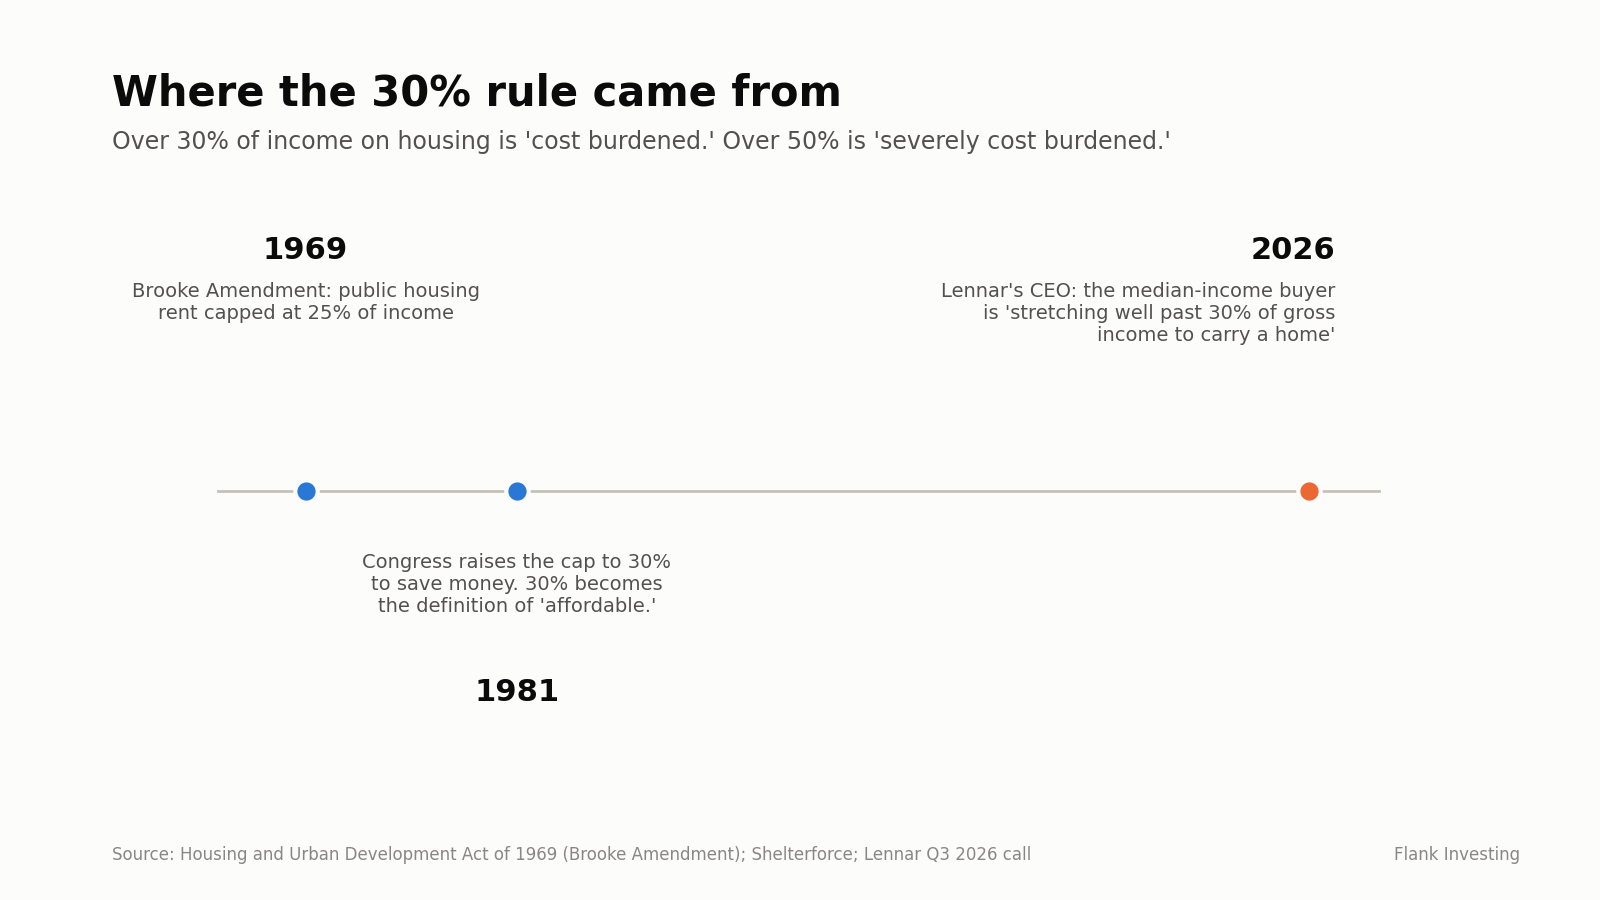
That 30% number isn't a law of finance.
In 1969, Congress capped rent in public housing at 25% of income, the Brooke Amendment. In 1981 it raised the cap to 30% to save money, and the number stuck. Today anyone paying more than 30% of income for housing is "cost burdened."
More than 50% is "severely cost burdened." So when Lennar's CEO says the median family is past 30%, he's saying the typical buyer is past the line the government drew for subsidized renters.
Pathetic (not Lennar's fault). Really hate that for my fellow young Americans.
So, is now a good time to buy a house?
with the literal home builders offering some of the highest discounts they've ever offered, let's look at whether now is a good time to buy a house, with the obvious elephant in the room being mortgage rates. One of the most common terms in real estate investing is “date the rate,” which I completely agree with, so long as you can afford your monthly mortgage charge (and it's well below the 30% gross income measure)
The reasons it might be a good time to buy a home :
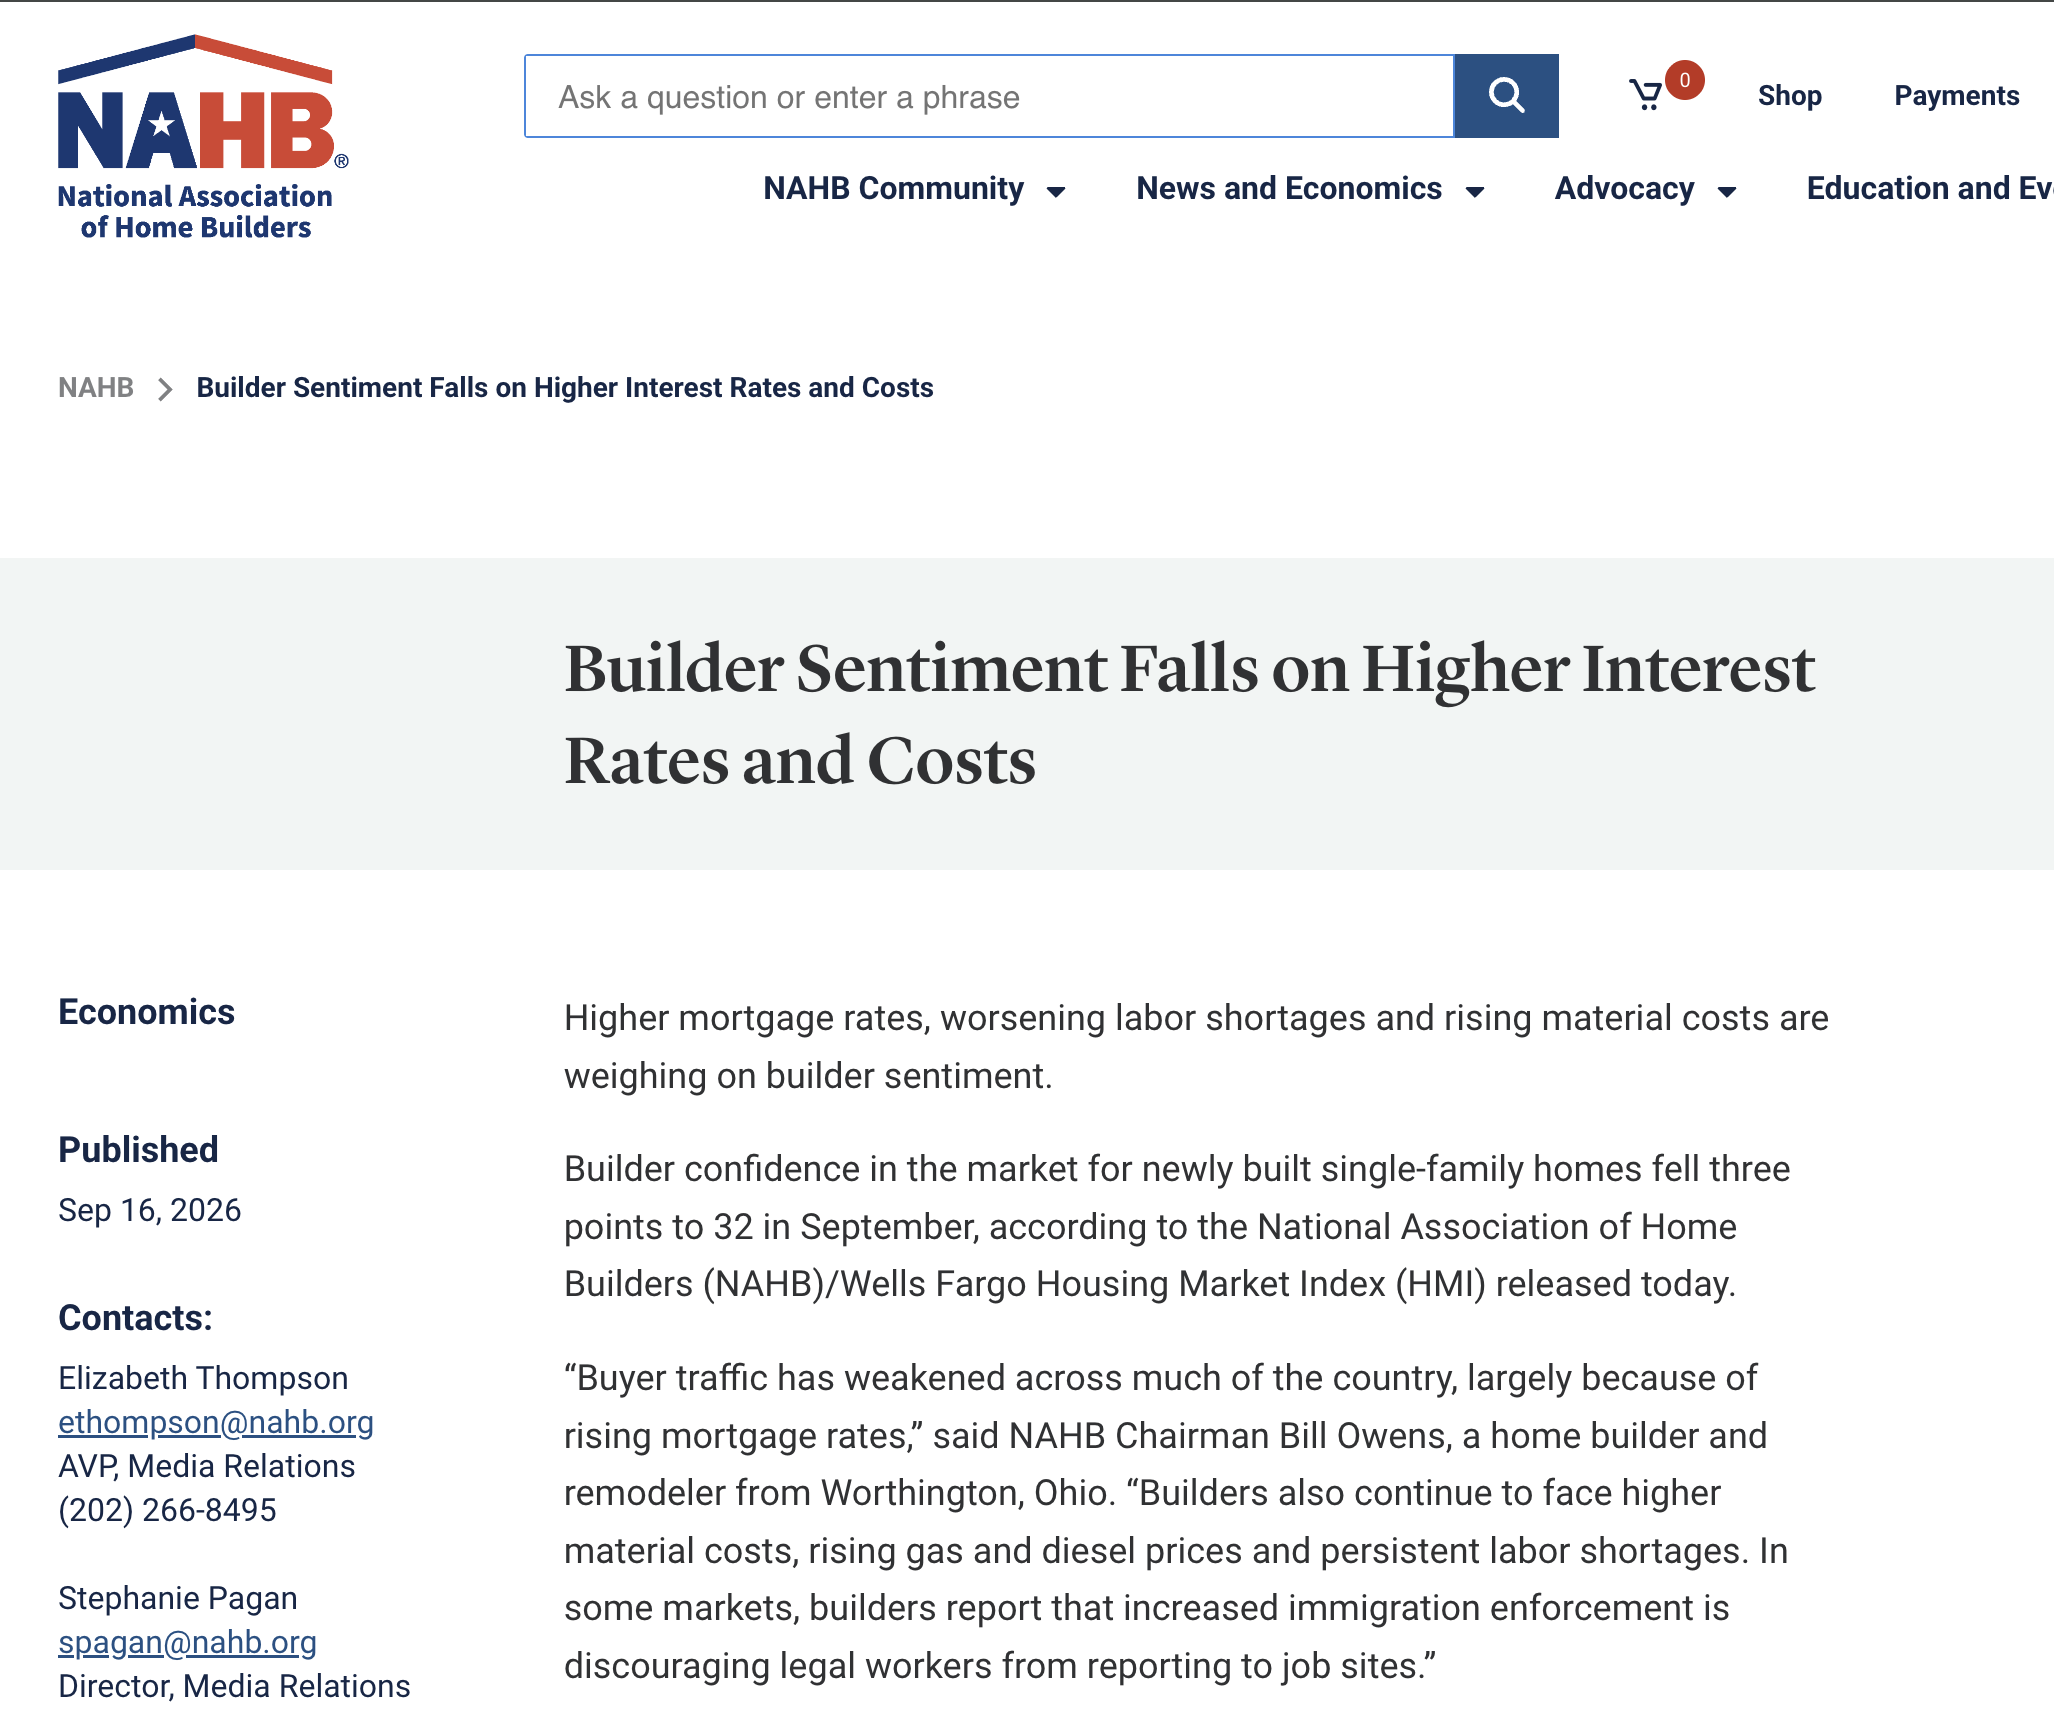
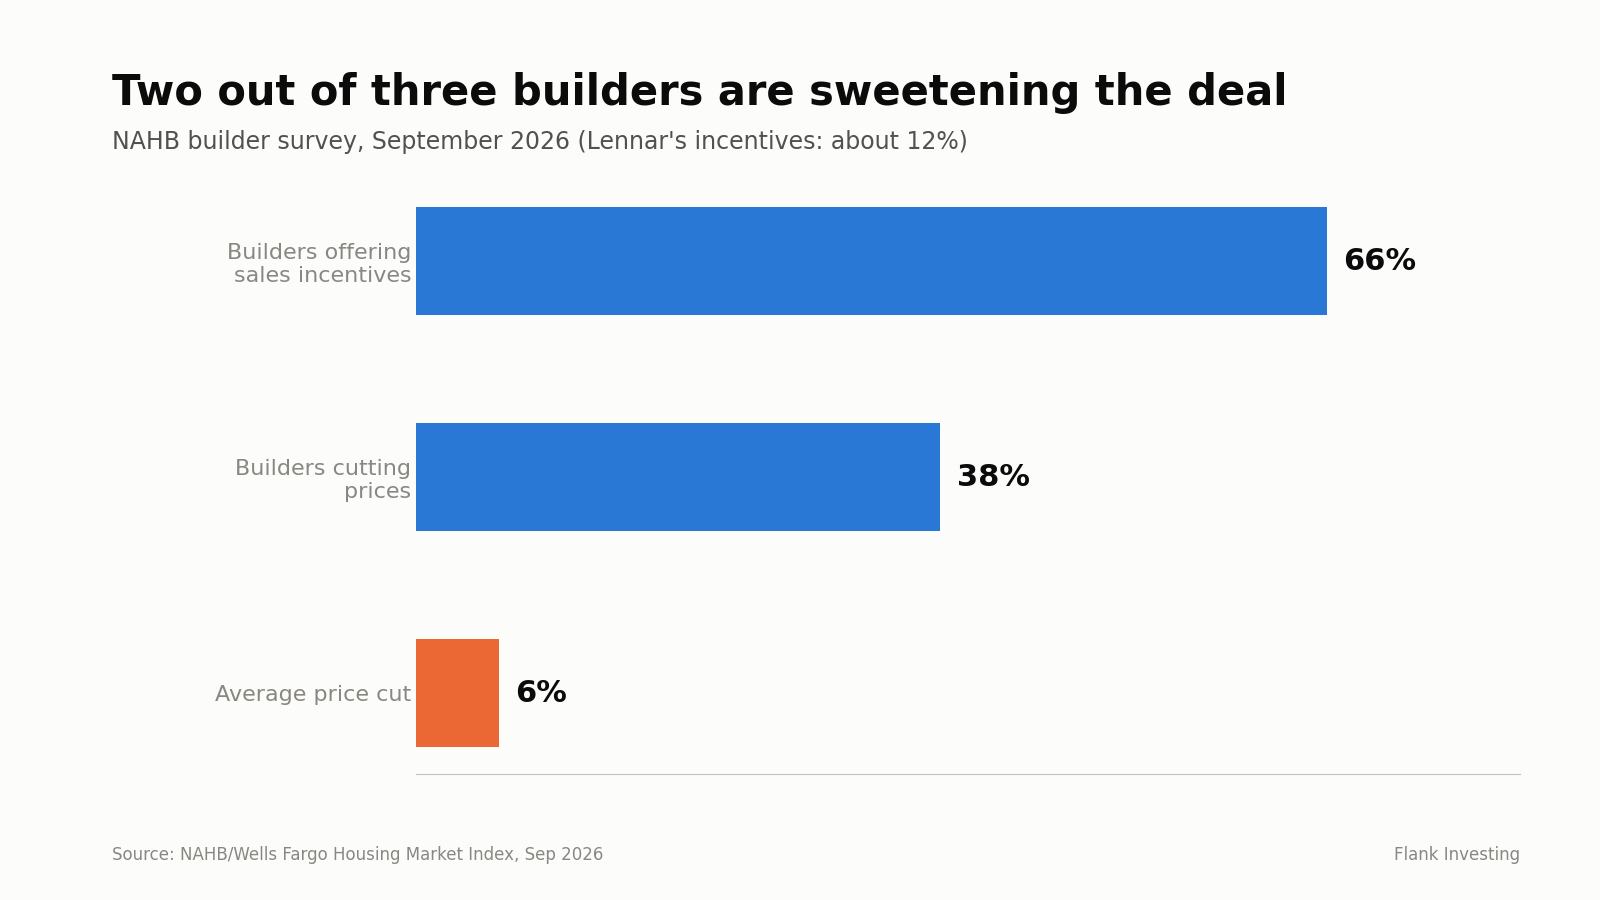
Builders are discounting hard. In September, 38% of builders cut prices, the average cut was 6%, and 66% offered incentives, per the NAHB survey. Lennar's at 12%.
It's a buyer's market for new homes.
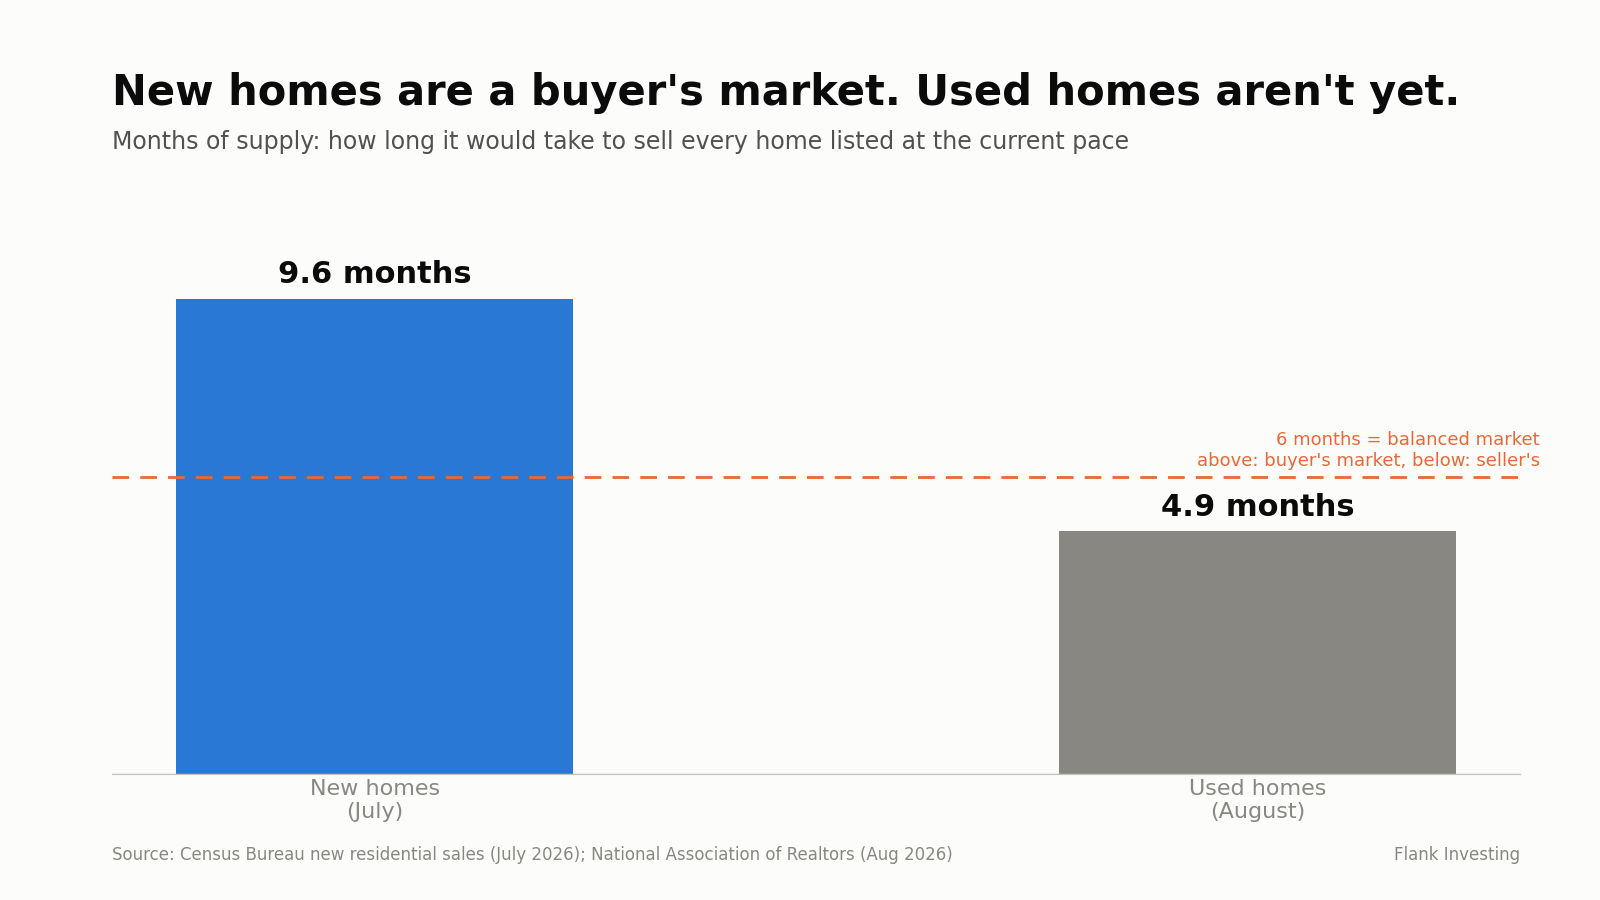
A rule of thumb I didn't know until this week: about six months of supply is a balanced market.
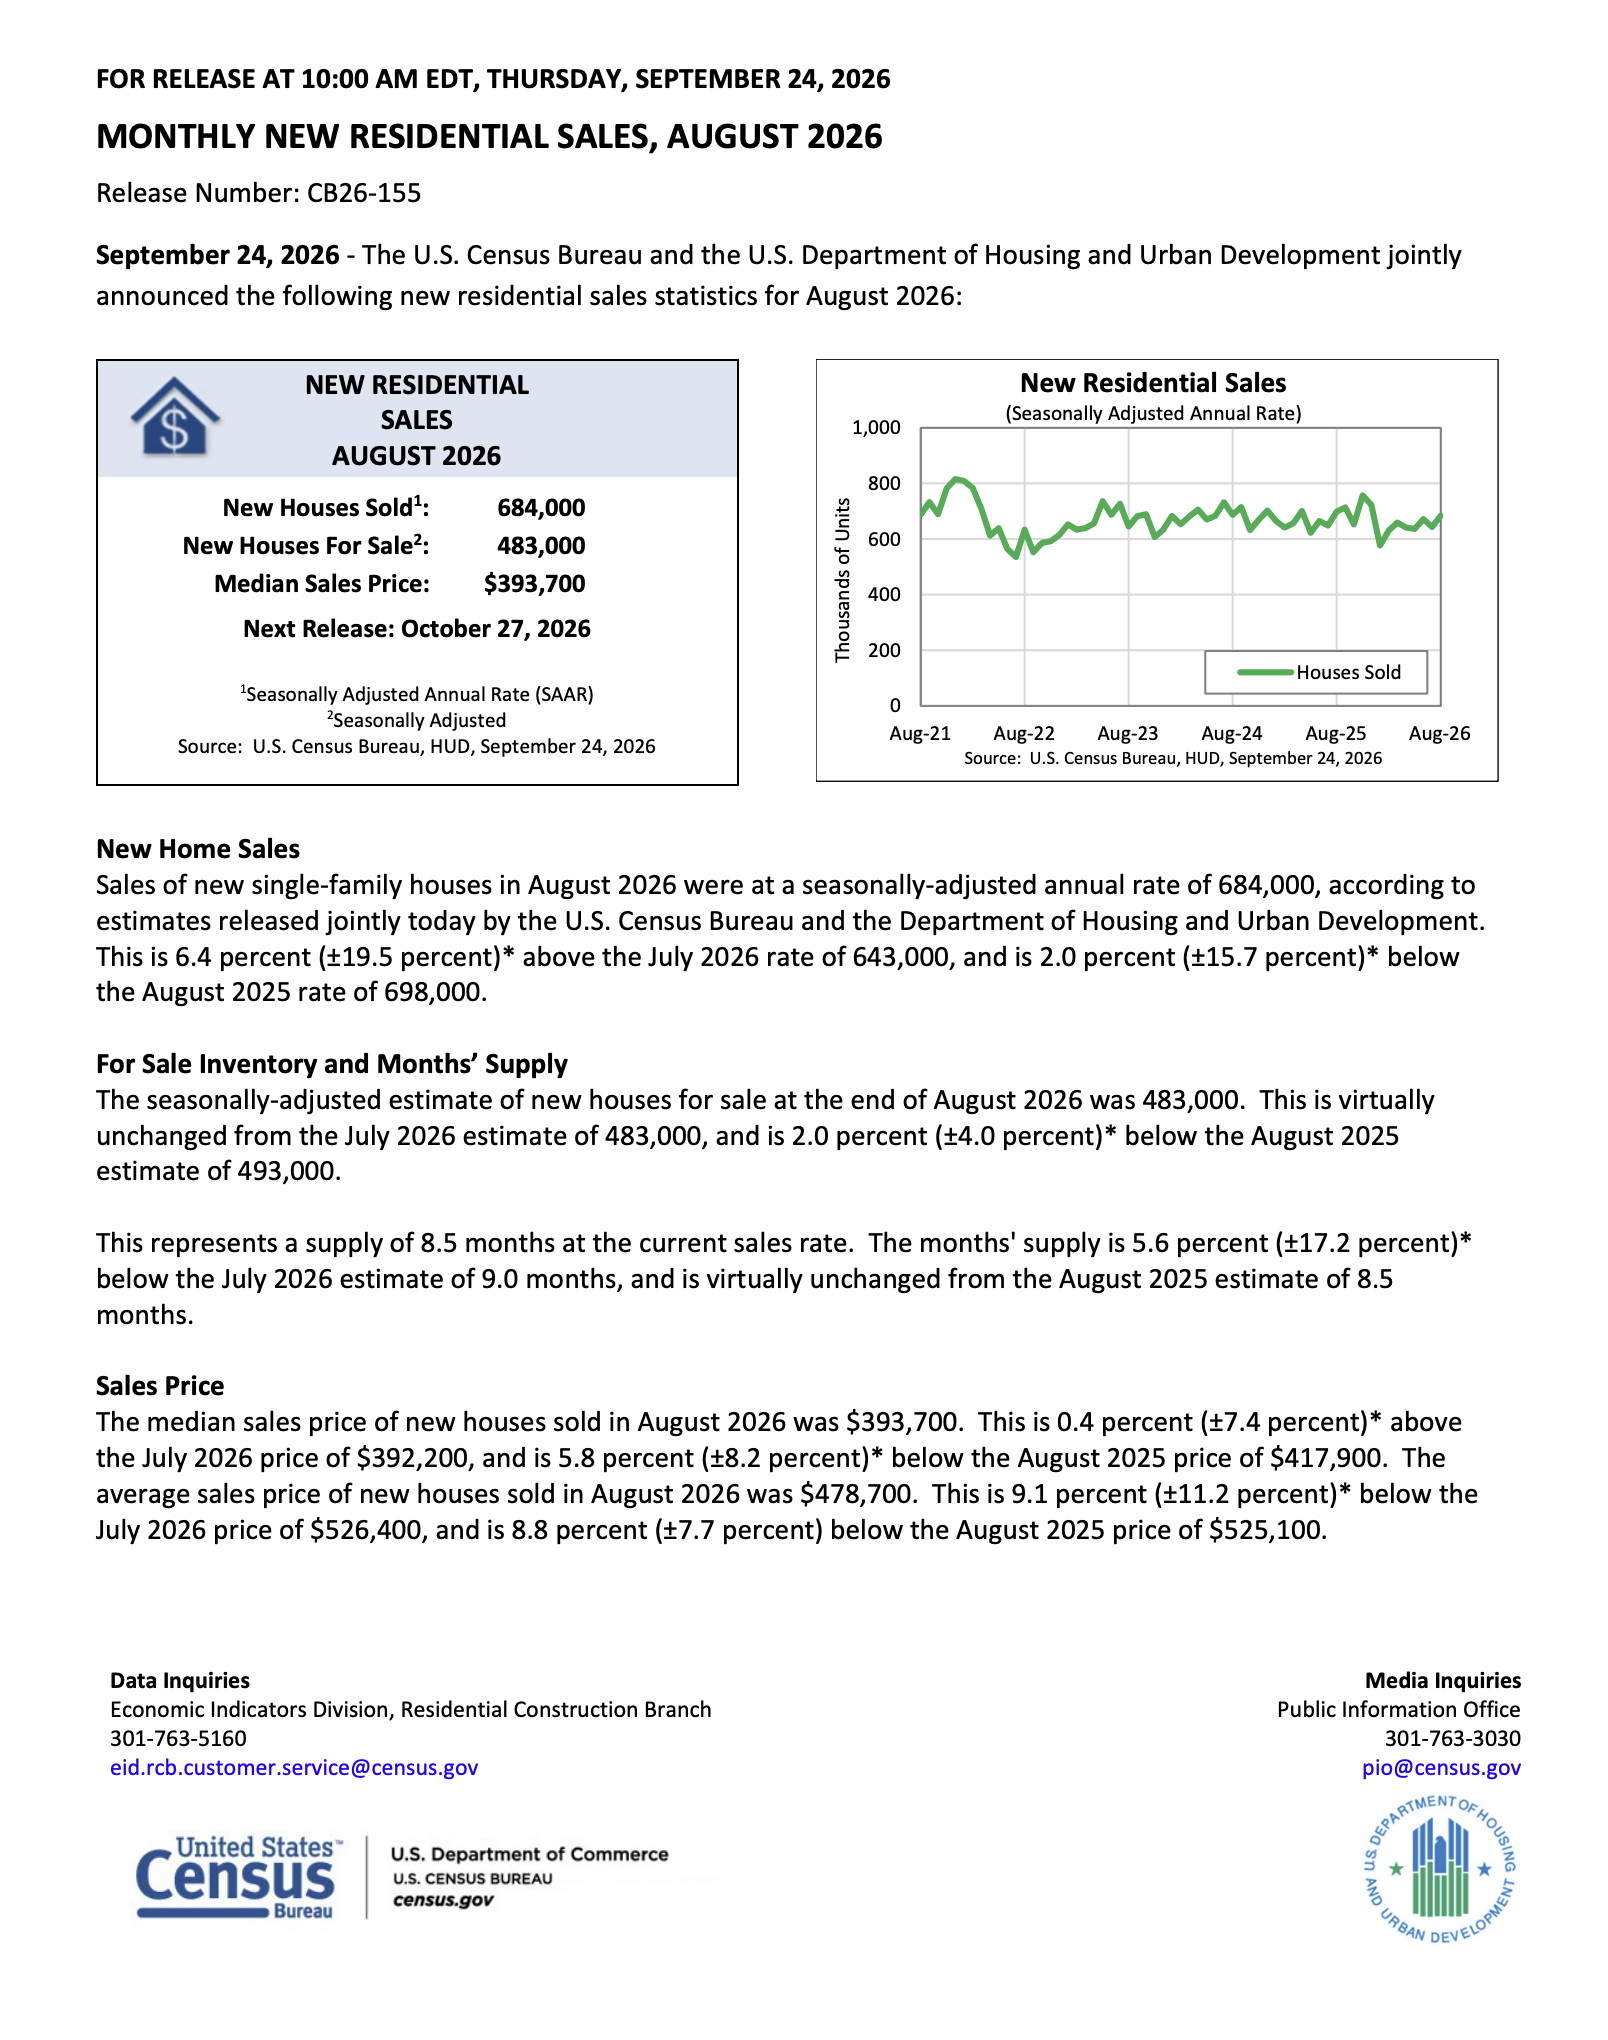
Above that, buyers have the power. New homes are sitting at 9.6 months of supply, with 488,000 unsold, per the Census Bureau. Used homes are at 4.9 months, so not quite there yet, but inventory is at its highest in over ten years, per NAR
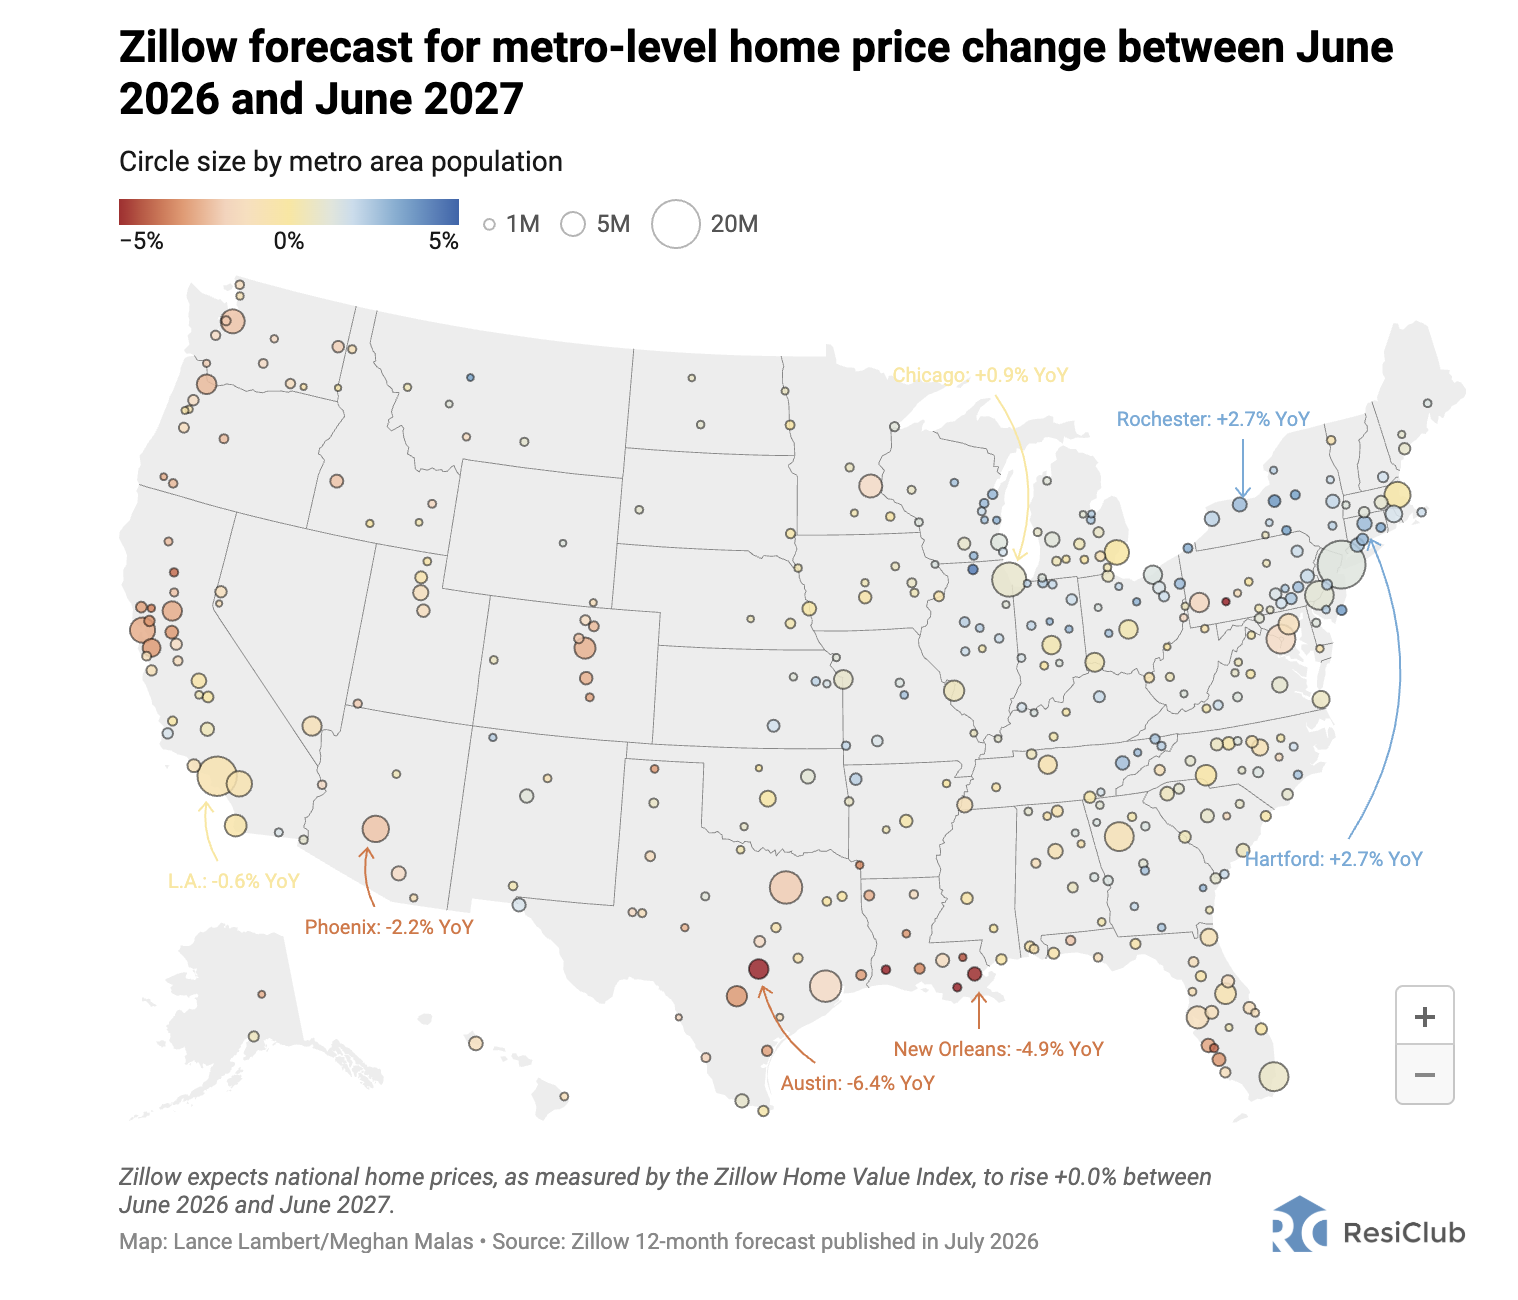
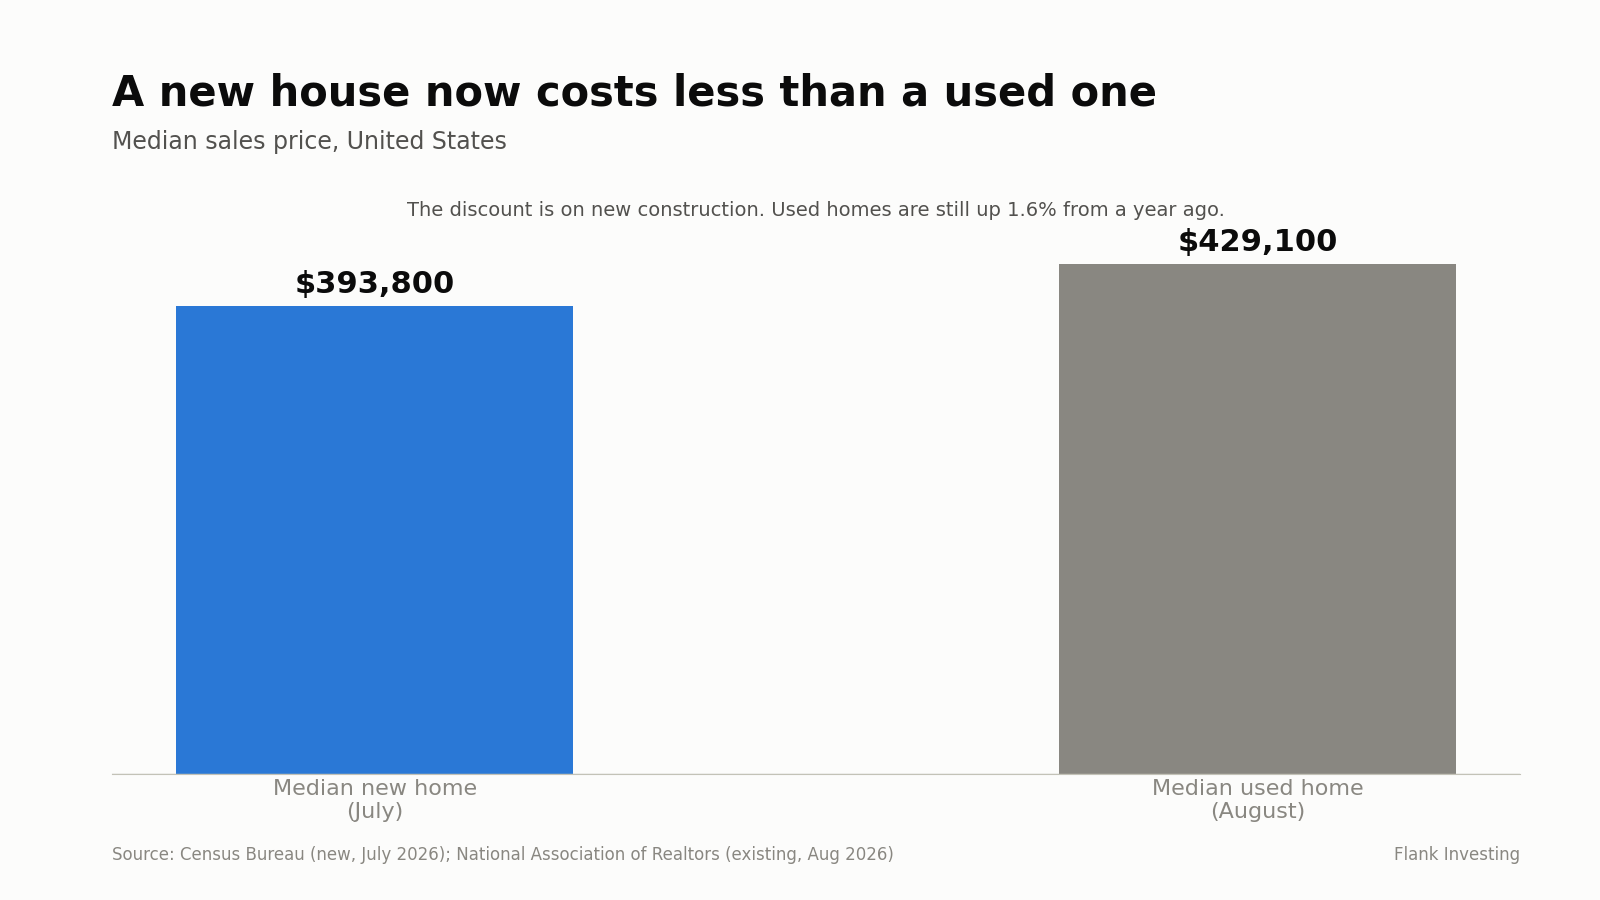
Prices have stopped running. The median used home is up 1.6% from a year ago. Zillow's forecast (https://www.fastcompany.com/91581818/housing-market-home-prices-zillow-just-revised-price-forecast-for-400-markets-see-the-map) for the next 12 months is 0.0%. And the median new home, at $393,800, now costs less than the median used one, at $429,100. The discount is in new construction.
And the guy cutting prices still says the fundamental shortage of housing hasn't been solved.
The reasons it might not be a good time to buy a home:
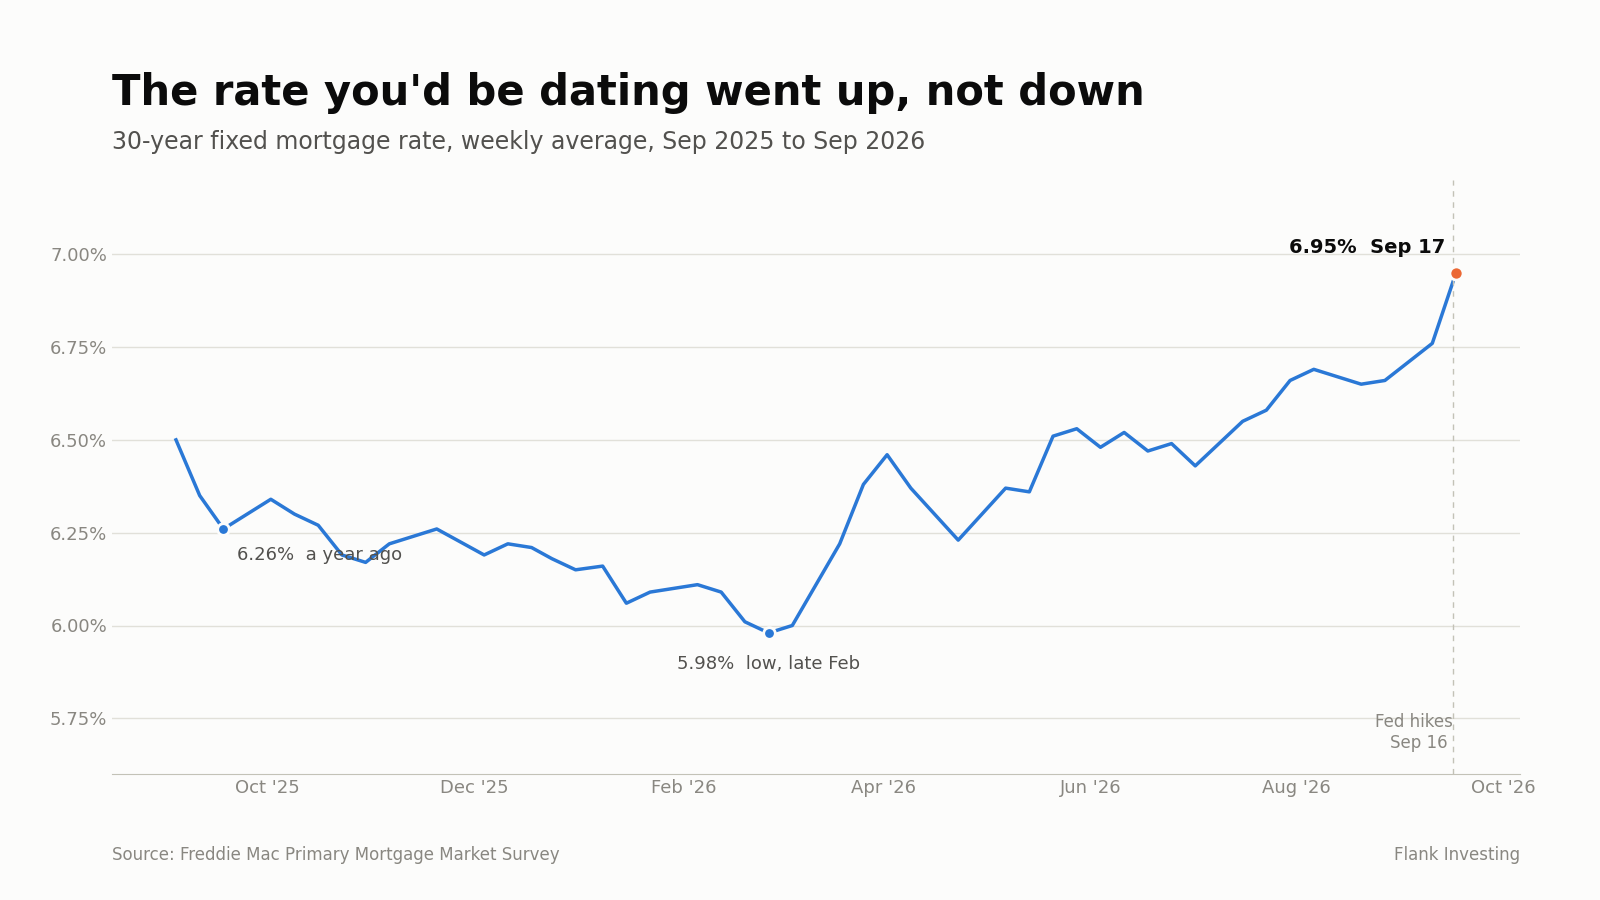
The rate is going the wrong way. My line for years has been "date the rate, marry the price." Buy the house at a fair price, refinance when rates drop. But the 30-year mortgage was 6.95% last week, per Freddie Mac , up from 6.26% a year ago, and the Fed raised rates on September 16 for the first time in three years. Dating the rate only works if the rate comes down. Right now it's going up.
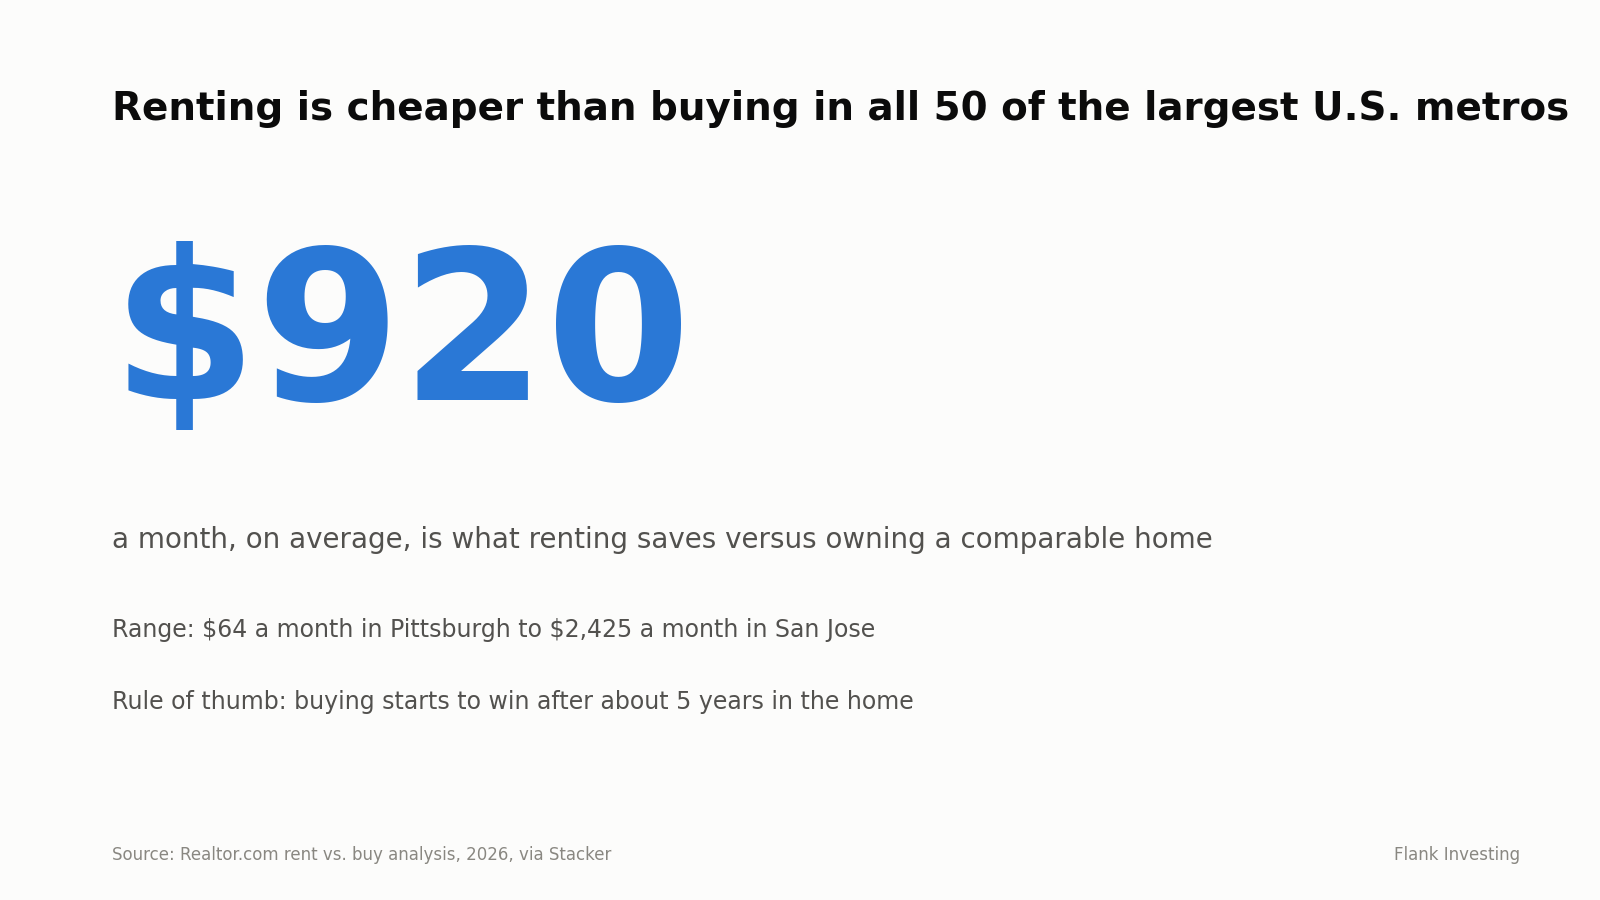
Renting is cheaper almost everywhere. A Realtor.com analysis found renting beats buying in all 50 of the largest U.S. metros, by about $920 a month on average. Buying usually starts to win after five or more years in the house. But you do have to remember that paying off your mortgage builds equity!
The discounts aren't working, so why would they stop? Lennar cut 12% and orders still fell 9%. Builder confidence is at a 12-month low. If you're buying new construction, next quarter's deal might be better than this one.
And read the fine print on the 12%. Part of it is Lennar buying down your rate, not cutting the price. Nice for the monthly payment, but the price you married is still the sticker price.
My thoughts
It depends, of course. But "it depends" is hiding two questions.
How long are you staying? Under five years, renting probably wins. The transaction costs eat you.
Can you carry it under 30% of your income at mortgage rates at 7%, without betting on a refinance?
If yes, and the house is priced for today's market, marry the price. If you need the refi to make the math work, you're not dating the rate. You're married to it.
This isn't theoretical for me. As you all may know, I had a son recently, and my mom is interested in moving to the small beach town where I live to be near him. We're trying to find her a home right now. So I'm running this exact math.
One last bit of David lore, and my biggest recommendation for anyone buying a first home. When my wife and I bought our first house in 2021, we Airbnb'd the first floor and lived on the second. For the first three years, the Airbnb covered about 125% of the total cost of owning the house. Mortgage, taxes, insurance, upkeep, all of it, plus 25%. I was effectively paid to live in my house. I can't recommend enough that people look for setups like that when it makes sense.
Sentiment: Too hard